Pricing power in the memory sector does not move in a straight line. It ebbs and flows with cycles of demand, supply, consolidation, and technological transition. At the same time, the industry’s structure — who holds how much market share — is not static either. One of the most useful ways to capture this structure is the Herfindahl-Hirschman Index (HHI), a simple but powerful concentration metric that can reveal how much leverage the leading players have at any given moment.
This post explores how cyclic pricing power shifts in DRAM, NAND, and emerging AI-focused memory can be read through the lens of the HHI, and how those structural patterns feed into ETF and index derivatives built around AI storage and computing power. The aim is not to deliver a rigid econometrics lecture, but to weave together market structure, cycles, and practical tools for investors who want to trade or allocate capital in this theme.
HHI: A Quick Structural Compass For Memory
The Herfindahl-Hirschman Index adds up the squared market shares of all firms in an industry, producing a single number that reflects how concentrated the market is. A fragmented industry with many small players will have a low HHI; an oligopoly dominated by a handful of giants will have a high one. Regulators often use thresholds (like 1,800 in the U.S.) to label markets as unconcentrated, moderately concentrated, or highly concentrated.
Memory markets sit firmly on the concentrated end of the scale. In DRAM, for example, three firms — Samsung, SK hynix, and Micron — have historically controlled around 90–95% of global share, yielding an HHI comfortably above 3,000 and signaling a clear oligopoly. NAND is more populated but still dominated by a relatively small set of major players. These structural facts matter because they shape pricing power: the more concentrated the market, the easier it is for suppliers to manage capacity and influence prices.
Cyclicality In A Concentrated World
Memory is notoriously cyclical. For decades, the sector has swung between boom and bust as bit demand, capacity expansions, and technological transitions collided. Yet the post-consolidation era, where HHI scores rose sharply, changed the character of these cycles. Oligopolistic DRAM, for example, has been able to enforce supply discipline more effectively than a fragmented market could.
The result is not the elimination of cycles, but a different rhythm. Upcycles can be longer and more profitable, driven by sustained pricing power rather than brief spikes. Downcycles can be shallower or more controlled, with major players cutting production or slowing capex to protect margins. Against this backdrop, the HHI becomes more than a static descriptor; it is a backdrop for reading how pricing power might behave in the next swing.
Reading Pricing Power Through HHI
How exactly does HHI relate to pricing power cycles? The relationship is not mechanical, but there are clear tendencies:
- Higher HHI, stronger baseline pricing power. In industries where the top three players control most of the market, coordinated discipline (even without explicit collusion) tends to support firmer price floors and more controlled discounting.
- Lower HHI, more competitive pressure. As more firms gain meaningful share, the temptation to gain volume through price cuts increases, making cycles more volatile and margins more fragile.
- Dynamic HHI, shifting leverage. Mergers, IPOs, regional policy shifts, and technology changes can move concentration metrics over time, altering how much negotiating power suppliers have relative to buyers.
In DRAM today, the HHI is firmly in “highly concentrated” territory, with some analyses suggesting an effective duopoly if you treat certain producers as part of a broader industrial bloc. This environment has coincided with extreme margin cycles, where pricing power drives outsized profits even as per-bit costs continue to fall. In NAND and emerging storage-class memory, concentration is different, and so is the pricing dynamic. ETFs and derivatives built on these segments need to respect those structural distinctions.
Case Study Feel: DRAM’s Oligopoly And ETF Implications
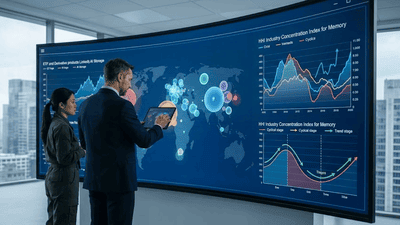
Treat DRAM as our primary case. The market’s high HHI signals that three names effectively control global supply. During periods of AI-driven demand for high-bandwidth memory — feeding GPUs, accelerators, and data center architectures — those firms have shown the ability to hold pricing, slow capacity additions, and defend margins even as unit volumes surge.
An ETF that focuses on memory stocks, or a broader AI storage and computing power ETF with heavy exposure to DRAM manufacturers, implicitly carries this structural leverage. When the cycle turns upward and the oligopoly exercises discipline, ETF holders can experience powerful positive surprise in earnings and share prices. Index derivatives linked to such an ETF can amplify or hedge that exposure, but the core engine is the structural pricing power reflected in DRAM’s elevated HHI.
Contrasts: NAND And Storage-Class Memory
NAND flash and storage-class memory present a different structural picture. NAND involves more players and has historically exhibited stronger price competition, with consolidation still underway and new technologies shifting the competitive frontier. Storage-class memory, meanwhile, is a fast-growing space where incumbents in DRAM and NAND mix with newcomers and diversified giants in persistent memory and specialized AI storage.
In these segments, HHI is lower or more fluid. Pricing power is less about a stable oligopoly and more about who leads in specific form factors, performance tiers, and integration into AI systems. Cycles can be driven by product transitions and adoption curves more than by pure supply discipline. For ETF and derivative strategies, this means more nuanced exposure: high concentration in one memory subsegment (DRAM) coexists with more dynamic, competitive landscapes elsewhere. A single AI storage ETF may need to balance these differing HHI regimes within one portfolio.
HHI As A Leading Indicator For Cycle Character, Not Direction
It is tempting to treat HHI changes as directional signals: rising concentration equals “buy,” falling concentration equals “sell.” Reality is subtler. HHI is better viewed as an indicator of cycle character — how sharp, long, or controlled a pricing cycle might be — rather than a direct guide to direction.
For example:
- In a highly concentrated DRAM market, an upcycle triggered by AI demand may sustain higher average selling prices (ASPs) for longer, producing prolonged margin expansion and more persistent ETF returns.
- In a less concentrated NAND market, the same demand shock might result in stronger early price moves followed by faster competitive erosion as more suppliers chase volume.
- In an emerging storage-class memory space, HHI might be shifting as new players enter or old ones consolidate, making early cycles more experimental and less predictable.
Index derivatives — futures, options, and swaps tied to memory or AI infrastructure indices — can be structured with these cycle characters in mind: longer-dated exposure where concentrated oligopolies dominate, more tactical or relative-value trades where competition is intense and transitions are faster.
Connecting HHI To ETF Construction And Weighting
ETF designers implicitly make structural decisions when they choose indices and weighting schemes. In a memory-themed ETF, giving heavier weight to DRAM giants means embracing a high-HHI segment, with all its attendant pricing power and cycle behavior. Adding more diversified storage players, controller vendors, and device makers broadens the exposure and lowers effective concentration.
Several design questions emerge:
- Should the ETF tilt toward high-HHI segments (DRAM) to capture pricing power, or aim for a blended exposure that resonates with broader AI storage themes?
- How should cap-weighted versus equal-weighted approaches interact with concentration? Cap-weighting naturally accentuates structural oligopolies; equal-weighting can diffuse them.
- Can HHI itself be a selection criterion, favoring industries or subindices with certain concentration ranges as part of a smart beta or thematic design?
Investors using such ETFs, and derivative traders building positions around them, benefit from understanding how these design choices echo the underlying HHI landscape. Concentration is not just a theoretical number; it shows up in how much the ETF relies on a handful of memory champions for its returns.
HHI And Directional Derivative Strategies
Derivative strategies around AI storage and computing indices often hinge on views about pricing power. For example, a trader who believes that DRAM’s current upcycle is structurally supported by an entrenched oligopoly — high HHI, disciplined capex, and tight capacity management — may choose longer-dated call options or swaps tied to a memory ETF or index.
Conversely, a trader worried that emerging competition or regulatory shifts will erode concentration might prefer relative-value trades: long diversified AI infrastructure indices, short memory-specific indices, or options strategies that express skepticism about sustained pricing power. In each case, HHI helps frame the argument:
- High and stable HHI supports strategies that assume pricing power persistence.
- Declining HHI or rising fragmentation invites strategies that bet on margin compression or more volatile cycles.
Because derivatives allow tailored exposure (specific maturities, strikes, or payoffs), HHI-informed views can be expressed in more focused ways than in simple spot ETF holdings.
Regional And Policy Dimensions: HHI Is Not Just Corporate
Memory concentration has a regional and policy overlay. Samsung and SK hynix are not only corporate players; they are part of a broader South Korean industrial strategy. Micron is embedded in U.S. strategic concerns around AI and advanced computing. Chinese entrants in DRAM and NAND add a geopolitical dimension to concentration metrics, as new capacity comes online under state-backed frameworks.
In some analyses, grouping certain firms by region changes the effective HHI. Treating Korean producers as a bloc can yield an even higher concentration measure, approaching an effective duopoly. Such perspectives affect how regulators, buyers, and investors read pricing power. For ETF and derivative strategies:
- Regional HHI views can shape country or currency exposure decisions.
- Policy risk — export controls, subsidies, industrial plans — can alter future HHI trajectories, impacting expectations of pricing power.
- Thematic products may choose to highlight or diversify away from particular regional oligopolies depending on investor preference.
Thus, HHI is not only a corporate statistic; it is a lens on the geopolitical architecture of memory supply, which is deeply relevant to AI storage and compute themes.
Future Shifts: AI, New Technologies, And Evolving Concentration
Looking ahead, AI itself may reshape concentration in memory. Demand for high-bandwidth memory (HBM), storage-class memory, and specialized persistent storage for AI workloads could either reinforce existing oligopolies or create opportunities for new players. If incumbents successfully own most of the new memory technologies, HHI remains high or even climbs. If disruptive entrants or diversified tech giants carve out significant share, concentration could ease.
For ETF and index derivatives:
- High-concentration futures: If the same players dominate DRAM, HBM, and SCM, memory-themed ETFs may lean more heavily on a small core, and pricing power upcycles could remain intense.
- Fragmentation scenarios: If new technologies invite more competition, index designs might broaden, and derivative strategies may shift toward volatility and spread trades rather than pure pricing power plays.
Investors can use evolving HHI metrics as an early signal of which path the memory sector is taking, calibrating their exposure to AI storage themes accordingly.
Practical Takeaways For Thematic Investors
For investors and traders operating in AI storage and computing power themes, HHI is a quiet but meaningful companion. Several practical takeaways emerge:
- Know the structural backdrop. Before trading options or futures on memory ETFs, understand how concentrated the underlying industry really is.
- Use HHI to shape expectations about cycle behavior, not exact price targets. Higher concentration supports longer, more controlled upcycles; lower concentration suggests sharper, more competitive swings.
- Align derivatives with structural views. If you believe in oligopoly-driven pricing power, longer-term, convex strategies (calls, structured swaps) may make more sense; if you expect fragmentation, relative-value and volatility trades may be more appropriate.
- Stay alert to structural change. IPOs, mergers, regional policy shifts, and technological breakthroughs can move HHI over time — and with it, the nature of pricing power.
Ultimately, cyclic pricing power shifts in memory are not just about spot price charts or quarterly earnings; they are about who owns the capacity, how disciplined they are, and how the industrial chessboard is arranged. The HHI gives these questions structure, turning market concentration into a number that can be tracked, debated, and — importantly for ETF and derivative users — traded against.
In the evolving story of AI storage and computing power, where data demands soar and hardware races to keep up, the memory sector will continue to sit at a leverage point in tech economics. Watching its concentration through the HHI, and reflecting those structural shifts in thematic ETFs and index derivatives, offers a way to connect abstract industry power maps with concrete investment decisions. It is a bridge between the shape of the market and the shape of the trade — a bridge worth crossing with eyes open and models flexible.